-
Shop
- Advanced Technologies
- AI Skills
- AI Skills for Creators & Freelancers
- AI Client Management
- AI Ethics
- AI Mindset
- AI Tools & Prompts
- AI Writing & Content Creation
- Audio, Voice & Music
- Design & Visual Creation
- Email, Messaging & Communication
- Freelancing & Business
- Marketing, Ads & Conversion
- Productivity, Workflow & Automation
- SEO & Search Optimization
- Social Media Content & Growth
- Strategy, Planning & Analytics
- Video Creation & Editing
- Apple Accessories
- Bathroom
- Beauty
- Best-Sellers
- Car Accessories
- Car Buying & Ownership
- Confidence
- Dating & Social Skills
- Digital Resources
- Education & Learning
- Family & Parenting
- Fashion
- Alexander McQueen
- Bags
- Balenciaga
- Blazers
- Bottega Veneta
- Brunello Cucinelli
- Burberry
- Chanel
- Chloé
- Dior
- Dolce & Gabbana
- Dresses
- Etro
- Fendi
- Gucci
- Jacquemus
- Jil Sander
- Kiton
- Luggage
- Miu Miu
- Off-White
- Outerwear
- Prada
- Rick Owens
- Saint Laurent
- Shoes
- The Row
- Tom Ford
- Valentino
- Valentino Garavani
- Versace
- Vivienne Westwood
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home Decor
- Home Electronics
- Home Styling & Organization
- Home Supplies
- Kids & Babies
- Kitchen
- Legend Footwear Brands Collection
- Lighting
- Luxury Brands Collection
- Online Business for Beginners
- Parenting & Child Development
- Patio, Lawn & Garden
- Personal Growth
- Personal Style & Fashion
- Pet Care
- Pet Lifestyle & Wellness
- Pet Supplies
- Pets
- Smart Amazon Shopping
- Smart Home Living Guides
- Super Deals
- Travel
- Travel & Adventure
- Wealth
- Wellness
- Popular
- Best deals
Declare Bank Interest Easily: A Stress-Free Checklist
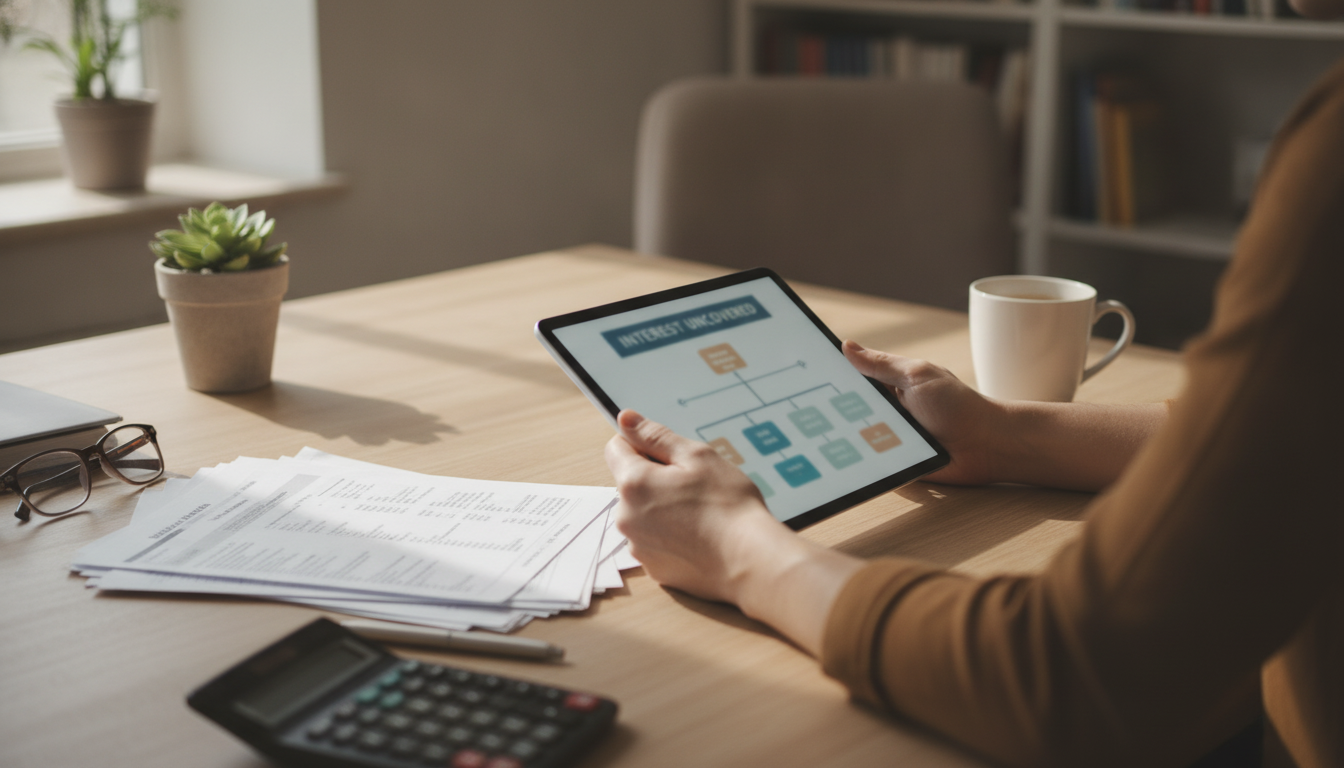
Interest Uncovered: A Clear, Stress-Free Way to Declare Bank Interest
Bank interest can look simple until it’s time to report it correctly—especially when multiple accounts, joint ownership, and tax-free allowances come into play. A clean process makes it easier to gather the right figures, avoid duplicate entries, and keep solid records in case questions come later.
What counts as “bank interest” (and what often gets missed)
Bank interest usually means the amount a financial institution credits to you for keeping money on deposit. The basics are straightforward, but a few situations commonly cause underreporting or mismatches.
- Typical sources: savings accounts, interest-bearing checking accounts, certificates of deposit (CDs), money market accounts, and fixed/term deposits.
- Online banks and fintech cash accounts: some issue a traditional interest tax form; others provide a year-end summary or route reporting through a partner bank. Confirm what document you’re meant to use.
- Joint accounts: interest is not always a simple 50/50 split. Allocation can depend on legal ownership, who contributed funds, and rules where you file.
- Foreign-currency interest: track the original amount and use an acceptable conversion approach for the reporting currency (and keep the source of the exchange rate used).
- Promotional bonuses: “new account” cash bonuses or rewards may be treated as taxable income and can appear on the same paperwork as interest—even when they don’t look like classic interest.
Common bank-interest paperwork and where to find it
| Document/Record | Where it shows up | Why it matters |
|---|---|---|
| Annual interest statement (tax form or year-end summary) | Online banking → Statements/Tax documents | Primary figure used to report interest income |
| Monthly account statements | PDF statements or mailed copies | Back-up records to reconcile totals and timing |
| Account opening/ownership details | Account profile, original paperwork, bank support | Helps confirm who should report the interest (especially joint accounts) |
| Foreign account statements | Foreign bank portal or mailed statements | Supports currency conversion and any separate reporting requirements |
| Interest certificates for term deposits/CDs | Investment/Deposits tab, maturity documents | Confirms interest accrual and payout dates |
Before filing: gather numbers once, then reuse them
The smoothest filings come from treating interest reporting like a small, repeatable audit: collect every account once, record the totals once, then reuse the list when you enter figures in your tax software or provide them to your preparer.
- Create a simple list of all accounts that earned interest during the tax year (including any that were closed).
- Download each account’s year-end interest summary. If a summary is missing, compile totals from statements.
- Record: account name, institution, ownership type (individual/joint/trust/business), interest amount, and the tax year it relates to.
- Check whether interest was credited but not paid out (some products accrue interest differently and may report on different schedules).
- Save documents in one folder (cloud + local) with consistent filenames like “BankName_AccountLast4_TaxYear.pdf”.
In the U.S., many banks issue Form 1099-INT when applicable; the IRS overview of what counts as interest income is a helpful reference: IRS Topic 403: Interest Income. For box-by-box detail on common interest reporting, see IRS Form 1099-INT and Instructions.
Step-by-step: declare bank interest without the confusion
Step 1 — Confirm the tax year window
Make sure you’re using the correct reporting period for where you file (most U.S. individual returns use a calendar year). Don’t assume the statement date equals the reporting year—use the tax year shown on the document.
Step 2 — Find the right place to enter interest
Whether you use tax software, a preparer worksheet, or a government return section, locate the area for “interest income” and note how it asks for payers (banks/institutions) and amounts.
Step 3 — Enter each payer and match the amount
Enter the institution name and interest amount exactly as supported by your year-end documents. If you have multiple accounts at one bank, confirm whether the bank issued one combined form/summary or separate ones.
Step 4 — Handle joint accounts correctly
Apply the ownership split required by local rules, and keep a short note explaining how you allocated it (for example, based on account agreement, contribution records, or a consistent household policy aligned with applicable rules).
Step 5 — Address special situations
Step 6 — Double-check totals
Step 7 — Save proof with your tax records
Common mistakes that trigger notices (and how to avoid them)
When the numbers don’t match: a quick troubleshooting checklist
A simpler path: the step-by-step eBook designed for everyday savers
Recommended reading:
Interest Uncovered: The Everyday Saver’s Guide to Declaring Bank Interest (Without the Headache)
For creators and solopreneurs who also track business accounts and want a streamlined approach to documentation habits, this companion resource may help:
AI-Powered Brand Magic: Craft Your Freelance Style Guide Fast
FAQ
Do small amounts of bank interest need to be declared?
It depends on local tax rules and any applicable thresholds, but many systems expect taxable interest to be reported even when it’s small. Your year-end statement or interest summary is the best way to confirm what was paid (or credited) for the year.
How is interest handled for joint bank accounts?
Allocation can depend on legal ownership and jurisdictional rules, and it isn’t always automatically split 50/50. Keep documentation showing how you determined the split and make sure the total across owners still reconciles to the bank’s statement.
What should be done if a bank issues a corrected interest statement?
Use the corrected figure for reporting and retain both the original and corrected documents with your records. If you already filed using the original numbers, review whether an amended return is needed based on the size and impact of the change.
Recommended for you

Organize a Room That’s Overstuffed: 6 Fast Steps
Jul 26, 2026



Leave a comment